Selling a home in Rochester starts with a clear plan for your property, your timing, and your next move. Use this overview to prepare for a conversation with Updegraff Group Realty, then download

Dated: February 21 2024
Views: 311
Smart Strategies for First-Time Homebuyers
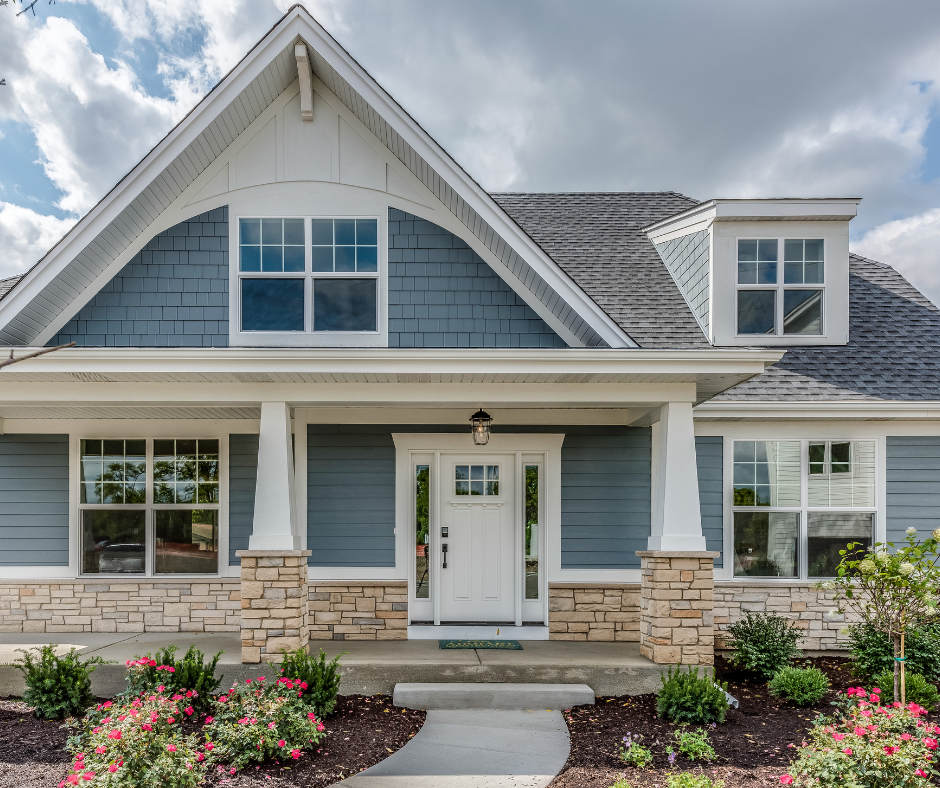
Leaping into homeownership for the first time is a thrilling milestone! While achieving this dream is entirely possible, it's essential to be aware of the challenges posed by today's housing market, such as the limited availability of homes for sale and ongoing affordability issues.
If you're prepared and eager to embark on the journey of buying your first home, here are some straightforward tips to help you make your dream a reality.
1. Save Money with First-Time Home Buyer Programs
Purchasing your first home comes with initial costs that can seem scary, like the down payment and closing costs. However, many assistance programs cater to first-time homebuyers, offering loans with minimal or no upfront expenses. According to Bankrate, these programs often feature more lenient requirements, such as lower down payments and credit score thresholds. Many even assist with closing costs and down payments through grants and low-interest loans. To explore these options further, reach out to our lender, Jacob Page, for more info.
2. Condos and Townhomes
In the current real estate landscape, a shortage of available homes has driven prices up, making affordability a challenge for buyers. One strategy to navigate this is to consider alternatives like condos and townhomes. These properties typically come with a lower price tag and have historically served as a stepping stone for buyers seeking a more economical entry into homeownership. While condos and townhomes may be smaller, they still offer the opportunity to build equity and provide a foothold in the market. According to Hannah Jones, Senior Economic Analyst at Realtor.com, these options can be particularly beneficial for buyers with limited budgets who are determined to start accumulating equity.
3. Multi-Generational Living
Another avenue to explore is a multi-generational living arrangement by purchasing a home with friends or family members— Pooling resources with loved ones allows for the sharing of expenses such as the mortgage and bills, making homeownership more attainable. Additionally, having multiple incomes involved can increase the likelihood of qualifying for a larger mortgage, which is especially advantageous in today's high-cost market. This collaborative approach not only eases financial burdens but also fosters a sense of community and support.
About Mark C. UpdegraffWelcome — I’m Mark C. Updegraff, Broker of Record and founder of Updegraff Group Realty.My path into real estate has been anything but ordinary, and that has become ....
Selling a home in Rochester starts with a clear plan for your property, your timing, and your next move. Use this overview to prepare for a conversation with Updegraff Group Realty, then download
Updated September 12, 2026. This guide revisits the topic of our June 2023 article for people considering their first Rochester investment property.Starting young gives you time to learn, but age
When you're planning to buy a house, your credit score plays a crucial role in determining your eligibility for a mortgage and the interest rate you'll receive. Did you know that the minimum credit
If you're thinking about buying or selling a home, mortgage rates are probably on your mind. That's because these rates play a big role in determining how much your monthly mortgage payment will be,
 The Greater Syracuse Association of REALTORS ®: The data relating to real estate on this web site comes in part from the Internet Data Exchange (IDX) Program of the CNYIS, powered by CNYIS. Real estate listings held by firms other than Updegraff Group LLC, are marked with the IDX logo and detailed information about them includes the Listing Broker's Firm Name. All information deemed reliable but not guaranteed and should be independently verified. All properties are subject to prior sale, change
or withdrawal. Neither the listing broker(s) nor this site's owner shall be responsible for any typographical errors, misinformation, misprints, and shall be held totally harmless.
© Central New York Information Service, Inc. All rights reserved.
Show More...
 The data relating to real estate on this web site comes in part from the Internet Data Exchange (IDX) Program of NYSAMLS. Real estate listings held by firms other than Updegraff Group LLC, are marked with the IDX logo and detailed information about them includes the Listing Brokers Firm Name.
Disclaimer: All information deemed reliable but not guaranteed and should be independently verified. All properties are subject to prior sale, change or withdrawal. Neither the listing broker(s) nor Updegraff
Group LLC shall be responsible for any typographical errors, misinformation, misprints, and shall be held totally harmless. © 2026 CNYIS, GENRIS, WNYREIS. All rights reserved.
Show More...
